
- Compare agents
- Online valuation
- Explore my area
- Home toolkit
- News & guides


- Estate agents by area
- Sold house prices by area
- Estate Agent ValuationRequest an in-person valuation with an agent to discover your property's true market value.
- Online Valuation ToolGet a free instant estimate of your home's value.
- EPC CheckerFind out if your home has a valid Energy Performance Certificate.
- Listing MonitorAlready on the market? See how your online property advert is performing.
- Estate Agent Fee CalculatorSee typical local agent fees, including VAT.
- Cost of Selling CalculatorPlan your budget for agent fees, legal work and moving.
- Stamp Duty CalculatorEstimate SDLT, LBTT or LTT for your next purchase.
- Selling guides
- Estate agent guides
- Mortgage advice
- Conveyancing guides
- Property news See All News & Guides
Agent shortlist
HouseWorth
- How much does subsidence devalue a property?
House selling tips11 September 2026
How much does subsidence devalue a property?
Kimberley Taylor
Writer & Researcher
Estimated reading time: 10 minutes
Table of contents
- 1. At a glance
- 2. What subsidence means for a property's value
- 3. Ongoing subsidence versus historical subsidence
- 4. How much does subsidence devalue a property?
- 5. When subsidence has a minor impact
- 6. Signs of subsidence to look out for
- 7. What causes subsidence?
- 8. How much does subsidence cost to repair?
- 9. Underpinning methods
- 10. Does underpinning bring value back?
- 11. Does insurance cover subsidence?
- 12. Selling a house with subsidence
- 13. Get the property assessed
- 14. Consider repairs before listing
- 15. Declare subsidence to buyers
- 16. Choosing the right estate agent
- 17. References
- 18. FAQs
At a glance
Subsidence can reduce what a home is worth, though the size of the effect depends on the severity, the cost of repairs and whether the problem is active or resolved. When asking how much subsidence devalues a property, industry estimates often point to a meaningful reduction for ongoing cases, sometimes limiting a sale to cash buyers. Once a property has been professionally underpinned and monitored, the impact on subsidence house value is usually far smaller.
What subsidence means for a property's value
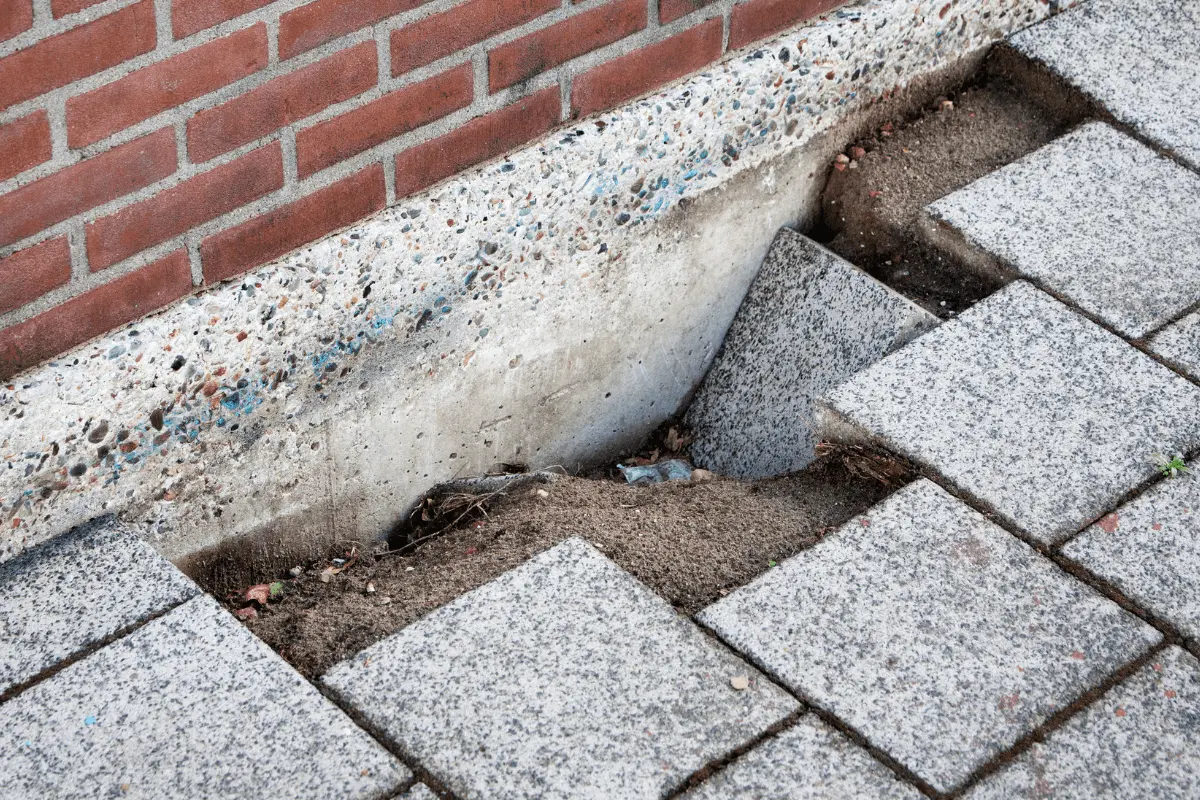
Subsidence happens when the ground beneath a building sinks, pulling the foundations downward with it. Because the foundations support the whole structure, even modest movement can affect walls, floors and extensions. This is why the question of how much subsidence devalues a property comes up so often for sellers, and why the answer varies so widely from one home to the next.
The value effect is driven less by the word "subsidence" itself and more by three things: how serious the movement is, whether it is still happening, and how much it may cost a buyer to put right. A home with a single, well-documented and fully repaired historical issue sits in a very different position from one with active, unresolved movement.
Ongoing subsidence versus historical subsidence
The distinction between ongoing and historical subsidence matters a great deal to buyers and lenders.
Ongoing subsidence means the ground is still moving and the property is still being affected. This tends to worry buyers most, because the eventual repair cost and outcome are uncertain.
Historical, or historic, subsidence means the movement has stopped, usually after repair and a period of monitoring. A home in this category is generally viewed as lower risk, and its value tends to hold up much better as a result.
How much does subsidence devalue a property?
There is no single figure that applies to every home, so treat any headline percentage with caution. Commonly quoted industry estimates suggest that unresolved, ongoing subsidence can reduce a property's value by around a fifth or more in serious cases, while minor or fully resolved issues may have little lasting effect. The right answer for your home depends on your survey and local market conditions.
A useful way to think about it is that the reduction often reflects the likely repair bill plus a buyer's allowance for risk and uncertainty. The table below sets out the main factors that push the effect up or down.
| Factor | Tends to reduce value more | Tends to reduce value less |
|---|---|---|
| Status | Ongoing, active movement | Historical, movement stopped |
| Repairs | Not yet carried out | Completed and documented |
| Cause | Complex (mining, drainage) | Straightforward (a single tree removed) |
| Evidence | No survey or paperwork | Full survey, guarantees, monitoring records |
| Buyer pool | Cash buyers only | Open to mortgaged buyers |
As a simple illustration, if a home might otherwise be worth £400,000 and a buyer expects repairs of around £40,000, they may factor at least that cost into their offer, alongside an allowance for the disruption and uncertainty involved. In more severe cases, where the structure is at real risk, the effect can be far larger, and a small number of homes may be very difficult to sell at all until the problem is addressed.
When subsidence has a minor impact
Not every case leads to a heavy reduction. Minor movement, often historical, may barely affect subsidence house value where the damage is limited and the cause has been dealt with. Where a property has been professionally diagnosed, repaired and underpinned by a suitable specialist, and where there is clear paperwork to show it, buyers are usually more comfortable, and the discount they seek tends to shrink.
Signs of subsidence to look out for
Spotting movement early gives you more time to take advice and manage any effect on value. Common indicators include:
- Diagonal cracks in walls, often wider at the top than the bottom, and typically appearing near doors and windows.
- Doors and windows that begin to stick or no longer fit their frames.
- Sloping or uneven floors.
- Walls that appear to lean or bow.
- Cracks where an extension meets the main house.
Not every crack points to subsidence, as many are simply the result of normal settlement or seasonal movement. If you are unsure, a chartered surveyor or structural engineer can assess what you are seeing. You can find an accredited professional through RICS.
What causes subsidence?
Understanding the cause helps you explain the situation to buyers and choose the right repair. Several factors can be involved, sometimes in combination.
The type of ground beneath a property plays a large role. Clay soils are a frequent factor because they swell when wet and shrink as they dry, which can move foundations over time. Sandy or silty soils can also contribute in some conditions.
Water is another common driver. A leaking drain or water main, heavy or prolonged rainfall, or long dry spells that lower the water table can all disturb the ground. Large trees and shrubs close to a building can draw significant moisture from the soil, which is why their roots are sometimes linked to movement.
The way a property was built matters too. Where ground was not fully prepared, or foundations were not designed for the load, the risk can be higher. In areas with a history of coal or mineral extraction, past mining can be a factor, and it is worth checking the ground history. Buyers and sellers in affected areas can order a coal mining report to understand the position.
How much does subsidence cost to repair?
Repair cost is often the single biggest driver of any reduction in value, which is why buyers focus on it so closely. When people ask how much subsidence costs to repair, the honest answer is that it depends on the cause, the depth of the foundations and the method used. A surveyor or structural engineer will recommend an approach suited to your property, and getting that professional assessment first is the sensible starting point.
Underpinning is one possible route for strengthening foundations, particularly in more serious cases, but the right repair depends on the cause of the movement. A surveyor, structural engineer or insurer may recommend other steps first, such as fixing drainage issues, removing the source of movement, or monitoring the property before structural works are carried out.
Underpinning methods
Mass concrete underpinning is often the most economical option. Soil is removed from beneath the affected foundation in sections and replaced with concrete, extending the foundation deeper to more stable ground.
Piled underpinning, sometimes called mini-piled underpinning, involves driving piles (steel or concrete shafts) deep into firmer ground and transferring the building's load onto them. It suits poorer soils and deeper foundations, and it can be quicker with less spoil to remove.
Beam and base underpinning is a more engineered approach. A reinforced concrete beam is installed to transfer the load onto concrete bases, and it can work well where loads need to be spread carefully.
Soil strengthening, such as resin or grout injection, stabilises the ground itself. It can be less disruptive in suitable conditions, though it is not right for every case.
Once the structure is stabilised, you may also need to repair the visible damage, such as cracks, along with any other affected finishes.
The figures below are indicative only, as real costs vary considerably by region, access and scale of work. Always base your budget on written quotes from qualified contractors.
| Underpinning method | Indicative cost (including VAT) |
|---|---|
| Piled** | From around £2,600 per m² |
| Beam and base | From around £2,000 per m² |
| Mass concrete | From around £1,500 per m² |
Does underpinning bring value back?
Underpinning can help restore value, because a repaired and monitored home is generally treated as historical rather than ongoing subsidence. Where work has been completed and documented, the lasting reduction is often modest.
Timing plays a part, though. Very recent underpinning can make some buyers cautious, as the property may still be within a monitoring period and long-term success is not yet proven. Insurance costs and excesses can also be higher immediately after works, which may feed into the offers you receive. As time passes and monitoring confirms stability, confidence usually improves.
Does insurance cover subsidence?
Buildings insurance often covers subsidence where the property has no history of previous issues, and it may cover the cost of repairing resulting damage as part of a claim. Policies differ, however, and a subsidence excess can be significant, so it is worth reading the terms carefully and speaking to your insurer.
If a property has a past subsidence claim, sits in an area at risk of coastal or riverbank erosion, or is due to undergo underpinning, cover may need to come from a specialist provider. Specialist policies can be arranged to cover repair works and, in some cases, alternative accommodation while the work is carried out. Cover and conditions vary by insurer, so confirm the details before relying on it.
Selling a house with subsidence
Selling a home with a subsidence history is very possible, though it helps to set realistic expectations from the outset. If you are looking beyond cash buyers, you may still need to price in a buyer's allowance for repairs and reassurance.
Get the property assessed
Before listing, it is generally worth commissioning a survey or a structural engineer's assessment. This clarifies the severity, the likely works and the cost, and it gives you documented evidence to share with buyers and agents. A clear, professional report often does more to protect your price than anything else.
Consider repairs before listing
Carrying out repairs before you market the home can widen your buyer pool and support a stronger price, since a repaired and documented property reassures both buyers and lenders. This is not right for everyone, as some sellers prefer to sell as-is to a cash buyer, but where the numbers work, completed and evidenced repairs tend to help. If speed matters more than price, selling to a cash buyer may be worth exploring.
Declare subsidence to buyers
Sellers are generally expected to be honest and transparent about known issues, including subsidence, and to record them accurately on the property information form along with supporting documents. Sellers and agents are also generally expected to provide clear, material information to buyers when marketing a home, and you can read more about the material information rules for property listings that apply. Withholding or misstating a known problem can lead a buyer to withdraw and may expose you to legal risk, so if you are unsure what to disclose, take advice from your conveyancing solicitor.
Being open also tends to build trust and reduce the chance of a sale collapsing late on, which protects both your time and, often, your final figure.
Choosing the right estate agent
An agent's experience counts for a lot when a property has a complex history. While a conveyancer should always advise on your legal position, an estate agent with strong experience selling homes with complications can help the process run smoothly, market the property honestly and manage buyer questions with confidence.
The lowest fee is not always the best value. What matters is finding an agent whose results justify what they charge. You can compare local agents by how they actually perform on price achieved against asking price and time to sell, which helps you choose on evidence rather than guesswork. It can also help to understand how mortgage affordability checks work for your likely buyers, since lending appetite affects who can make an offer.
References
FAQs
There is no fixed figure, because it depends on how serious the movement is, whether it is ongoing or historical, and the likely repair cost. Industry estimates commonly suggest a meaningful reduction for active, unresolved cases, sometimes limiting a sale to cash buyers, while minor or fully repaired issues may have little lasting effect. A helpful way to think about it is the probable repair bill plus a buyer's allowance for risk. The most reliable guide for your own home is a professional survey combined with current local market conditions, which together give a realistic picture of the likely effect on value.
Yes, homes with subsidence are sold regularly, though it helps to prepare. Getting a survey or structural engineer's report gives you documented evidence to share, which reassures buyers and lenders. You can choose to complete repairs before listing, which usually widens your buyer pool and supports a stronger price, or to sell as-is, which may point you toward cash buyers who accept the works. Pricing realistically and being open about the history both tend to help a sale progress. An experienced local agent can market the property honestly and handle buyer questions, which often makes the difference between a smooth sale and a stalled one.
Underpinning can help restore value, because once a home has been repaired and monitored, it is generally treated as historical rather than ongoing subsidence, which buyers view as lower risk. The lasting reduction is often modest where the work is documented with guarantees and monitoring records. Timing matters, though. Very recent underpinning can make some buyers cautious, since the monitoring period may still be running and long-term stability is not yet confirmed. Insurance premiums and excesses can also be higher soon after works. As time passes and monitoring shows the property is stable, buyer confidence usually improves and the effect on value tends to ease.
It depends on the lender and the circumstances. Some lenders are cautious about active, ongoing subsidence and may decline, which is one reason unresolved cases can end up appealing mainly to cash buyers. Where the issue is historical, has been professionally repaired and comes with clear documentation and monitoring records, more lenders may be willing to consider it, sometimes subject to a satisfactory survey or specific conditions. Because policies vary widely, it is worth checking directly and speaking to a mortgage adviser early. Buyers will often want to understand a lender's position before committing, so having your paperwork ready can help keep a sale moving.
Buildings insurance often covers subsidence where a property has no previous history of it, and it may cover repairing the resulting damage as part of a claim. Terms differ between insurers, and the subsidence excess can be substantial, so it is worth reading the policy carefully. Where a home has a past claim, sits in an area at risk of coastal or riverbank erosion, or is due to be underpinned, cover may need to come from a specialist provider. Specialist policies can be arranged to cover repair works and sometimes alternative accommodation during works. Because cover and conditions vary, confirm the details with your insurer rather than assuming a standard policy will respond.
Repair cost depends on the cause, the depth of the foundations and the method chosen, so it is difficult to give a single figure. Underpinning is the usual approach, and methods range from mass concrete, which is often the most economical, to piled underpinning, which suits deeper foundations and poorer soils and tends to cost more. Beam and base and soil strengthening, such as resin injection, sit within this range depending on conditions. On top of stabilising the structure, you may need to repair visible damage such as cracks. The most reliable way to budget is to get a professional assessment first, then obtain written quotes from qualified contractors for the specific works your property needs.
Sellers are generally expected to be honest about known issues, including subsidence, and to record them accurately on the property information form with supporting documents. Sellers and agents are also generally expected to give buyers clear, material information when marketing a home. Withholding or misstating a known problem can cause a buyer to withdraw and may expose you to legal risk, so transparency protects you as well as the buyer. Sharing your survey results and any repair paperwork tends to build trust and reduce the chance of a sale collapsing late on. If you are unsure exactly what needs to be disclosed in your situation, your conveyancing solicitor can advise you.
Early indicators often include diagonal cracks in walls, typically wider at the top and appearing near doors and windows, along with doors and windows that begin to stick. Sloping floors and walls that seem to lean or bow can also point to movement, as can cracks where an extension joins the main house. Not every crack means subsidence, since many result from normal settlement or seasonal changes in the building. If you are concerned, a chartered surveyor or structural engineer can assess the cause and advise on next steps. Catching movement early gives you more time to take advice, plan any repairs and manage the effect on your property's value.
Thinking about
selling your home?
Picking the right estate agent is vital for a successful sale. GetAgent makes choosing simple. Discover the best performing agents in your area.
- Free
- Data-driven
- No obligation
Thinking about
selling your home?
Picking the right estate agent is vital for a successful sale. GetAgent makes choosing simple. Discover the best performing agents in your area.
- Free
- Data-driven
- No obligation

Compare estate agents
It takes 2 minutes.


Get in touch
020 3608 6556
Our lines are closed
We are a company registered in England & Wales, company number 09428979.
Copyright © 2026 GetAgent Limited